Used Combine Financing: What Lenders Look For
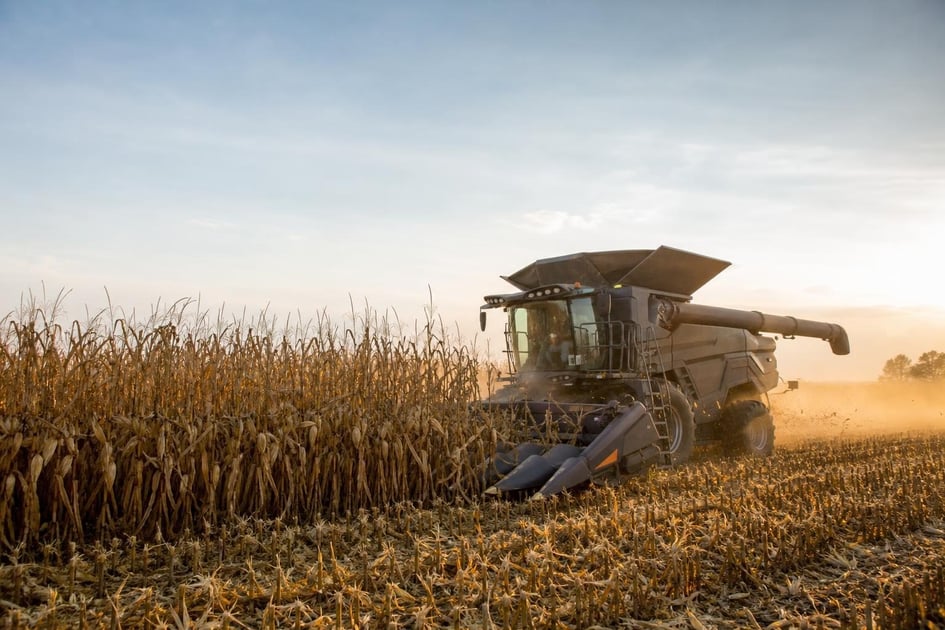
When it comes to combines financing used, the process works almost exactly like financing any other piece of agricultural equipment. The lender secures the loan with the machine itself, which keeps rates competitive and lets borrowers preserve working capital for seed, chemicals and labor. At Provide Capital, we finance used combines from $5,000 up to $5 million, with same-day approvals possible when the file is complete.
Because the combine is the collateral, the underwriting focuses on three things: your credit profile, the equipment’s condition and age, and the structure of the deal. A strong file in all three areas gets the best terms. A weakness in one area can often be offset by strength in another.
Credit and Time in Business
Most used combine approvals go to operators with at least two years in business and a credit score above 600. That is not a hard cutoff, but it is the band where most competitive offers sit. If your score is lower, a larger down payment or a shorter term can still get the deal done. Rates vary by credit profile, equipment age and term, so a borrower with a 720 score and a 3-year-old machine will see a different range than a borrower with a 640 score buying a 12-year-old unit.
Equipment Age and Hours
Lenders like to see the combine outlast the loan. A 15-year-old machine with 4,000 separator hours is a harder collateral case than a 6-year-old machine with 1,200 hours. Many programs cap equipment age at 10 to 15 years at origination, though exceptions exist for low-hour, well-maintained machines or deals with larger down payments. Serial-number verification, hour-meter photos and a condition report from the seller all help the underwriter get comfortable.
Down Payment and Collateral
Down payments on used combines typically range from 10% to 20% of the purchase price. A 20% down payment strengthens the loan-to-value ratio and often unlocks longer terms. Because the combine itself secures the financing, you usually do not need to pledge real estate or other unrelated assets. That is one reason Combines financing remains popular with row-crop and custom-harvest operators who want to keep their land equity untouched.
Key Insight: A combine with over 3,000 separator hours will usually require a larger down payment or a shorter amortization, even if the machine is only eight years old. Lenders underwrite hours harder than model year because engine and rotor wear drive future repair risk.
Get a fast decision on your equipment
Applying takes just a few minutes, and decisions can come as soon as the same day.
Start Your ApplicationNew vs. Used Combines: When Pre-Owned Makes Sense
A new Class 8 combine can run $750,000 or more once headers and technology packages are included, according to reporting on current farm equipment costs. A three- to five-year-old used model with similar capacity often sells for 40% to 60% less. For an owner-operator adding acres or replacing a worn-out machine, that spread can be the difference between cash-flowing the first season and running tight.
| Factor | New Combine | Used Combine (3–5 Years) |
|---|---|---|
| Upfront capital | $600,000–$750,000+ | $200,000–$400,000 |
| Depreciation curve | Steepest in years 1–3 | Flatter; slower value loss |
| Technology | Latest precision ag, telemetry | Prior-gen guidance still capable |
| Maintenance | Warranty coverage standard | Out-of-warranty; inspect records |
| Financing term | Up to 7 years common | 3–5 years typical; 7 possible |
| Down payment | Often 10–15% | Often 15–20% |
The biggest risk with used is hidden repair cost. A $250,000 combine that needs $40,000 in rotor, feeder-house and hydrostat work in the first season is no bargain. Before you commit, get a third-party inspection and review the maintenance log. If the seller cannot produce records, treat that as a signal, not a small detail.
Pro Tip: Buy used combines in late fall or early winter, right after harvest. Dealers and custom harvesters are most motivated to move inventory before year-end, and private sellers often list machines once they know their annual hours. Prices firm up by March as planting season nears.
Lease vs. Loan: How to Structure the Deal
Most used combine transactions are structured as equipment finance agreements—fixed-term loans with a $1 buyout at the end. You own the machine, take the depreciation and build equity. A true lease, or fair-market-value lease, is less common on used agricultural equipment because the residual is harder to predict, but it can make sense if you plan to trade every two or three seasons and want the lowest possible payment.
Equipment Finance Agreement
An EFA puts the title in your name day one, subject to a UCC lien. You deduct the interest and depreciation, and at the end of the term you own the combine free and clear. Terms generally run 36 to 84 months. Because the equipment itself is the collateral, you do not need to cross-collateralize your farm real estate.
Fair-Market-Value Lease
An FMV lease treats the combine as a rental for tax purposes. You write off the full lease payment, but you do not own the machine at the end unless you exercise a purchase option set at fair market value. This works best when you need a low payment today and expect to upgrade quickly. It is harder to obtain on used equipment over five years old because the lessor cannot underwrite the residual with confidence.
If you are unsure which structure fits your tax picture, talk to your CPA before you sign. The choice between deducting interest and depreciation versus deducting lease payments can swing your tax year 2026 liability by thousands of dollars.
See what you qualify for on a used combine and compare loan versus lease structures side by side.
Tax Treatment for Tax Year 2026
For tax year 2026, Section 179 allows a first-year deduction on qualifying used farm equipment, subject to annual inflation-adjusted limits. Because the exact dollar ceiling and phase-out threshold change each year, you should confirm the current numbers with your CPA before you close. Used combines qualify as long as they are new to you and placed in service during 2026.
Bonus depreciation may also apply, though the percentage has been stepping down from prior-year peaks. If bonus depreciation is available at 40% or lower for 2026, you will need to run the math against regular MACRS depreciation to see which route saves more over the holding period. Again, your CPA can model this in minutes.
The key point: financing does not change your eligibility for Section 179 or bonus depreciation. Whether you pay cash, use an equipment loan or enter a capital lease, the IRS generally treats the transaction as a purchase for depreciation purposes. A true operating lease is different—payments are expensed, not depreciated—so structure matters.
Cost Example: Running the Numbers on a Used Combine
Below are two realistic scenarios for used combine financing. These are illustrative ranges; your actual payment will depend on credit profile, equipment age and term.
Scenario A: Mid-Range Used Combine
- Purchase price: $220,000
- Down payment: 15% ($33,000)
- Amount financed: $187,000
- Term: 60 months
- Estimated monthly payment: $4,200–$4,900
Scenario B: Newer Low-Hour Combine
- Purchase price: $380,000
- Down payment: 20% ($76,000)
- Amount financed: $304,000
- Term: 72 months
- Estimated monthly payment: $5,800–$6,700
Notice how a larger down payment and a longer term interact. In Scenario B, the higher down payment keeps the monthly obligation manageable even though the machine costs nearly twice as much. If you need to preserve cash, you can reduce the down payment, but expect the payment range to shift upward and the term to shorten.
By the Numbers: A used combine kept for seven seasons and run 400 hours per year will accumulate 2,800 hours. Most lenders view 2,500 to 3,000 hours as the threshold where collateral value and repair risk start to diverge sharply, which is why terms beyond five years become harder to find on high-hour machines.
Find the right financing structure
Tell us about the equipment you need and we will show you the options that fit your business.
See Your OptionsIndustry Context: Why Used Combines Move in Cycles
The used combine market is seasonal and regional. Prices soften after harvest when custom operators and dealers offload inventory. They firm up in spring when planting deadlines reduce shopping time. If you are buying from a dealer in the Corn Belt, expect a 5% to 10% price premium over a private sale in the same condition, but also expect some warranty or reconditioning support.
Right-to-repair has also changed the calculus for used buyers. Under a recent FTC settlement with John Deere, farmers and independent shops now have broader access to software and diagnostic tools. That matters when you are evaluating a 2019 or 2020 model whose proprietary displays and sensors were previously locked behind dealer-only service contracts. Lower repair barriers help preserve the resale value of used machines and reduce the total cost of ownership.
Nationwide, row-crop and small-grain producers drive most combine demand, but regional specialties matter. In the Northern Plains, large rotary combines dominate. In the Mid-South, smaller class machines handle rice and soybeans. Wherever you farm, Agriculture equipment financing needs to match your crop calendar, not just your balance sheet.
Common Mistakes Buyers Make
Ignoring Separator and Engine Hours
Model year is easy to verify. Hours tell the real story. A 2018 combine with 3,500 hours may be closer to a major overhaul than a 2015 model with 1,800 hours. Always ask for the hour meter photo and service records before you apply for financing.
Buying Too Old for the Term
If you want a five-year loan, the combine should have enough useful life left to cover the note plus a buffer. A 12-year-old machine on a 60-month term means you are paying for it until it is 17. Most lenders will either shorten the term or ask for more money down. Rates vary by credit profile, equipment age and term, so age affects both availability and pricing.
Skipping the Title and Lien Search
Used combines sold at auction or through private parties can carry hidden liens. A UCC search and a clean title transfer protect both you and the lender. Provide Capital handles this as part of funding, but you should verify it is in process before you haul the machine home.
Underestimating Transport and Setup
A $220,000 combine can cost $3,000 to $8,000 to move across two states, plus another $1,500 to $3,000 for header hookup, software updates and calibration. Some borrowers finance these soft costs; others pay cash. Either way, build them into your budget before you set your down payment.
What Documentation You Need
A complete file speeds approval. Gather these items before you apply:
- Personal and business credit application
- Equipment description, including make, model, year and serial number
- Seller information and purchase agreement or invoice
- Proof of insurance naming the lender as loss payee
- Most recent two years of tax returns or bank statements (for larger requests)
- Hour-meter reading and maintenance records, if available
For requests under $150,000, some programs require only a one-page application and the equipment details. For requests above $500,000, expect to provide full financials and a brief operating history. Same-day approvals are possible when the file is clean and complete.
What Happens After Approval
Once approved, you will receive a term sheet outlining the payment, term, down payment and any conditions. Review it, sign and return the documents. The lender then performs a final collateral verification—often a photo review or an equipment inspection—and funds the deal. Funding usually occurs within 24 to 72 hours of final document receipt.
After funding, the lender files a UCC-1 financing statement against the combine. You receive the title or bill of sale showing the lender’s lien. Your first payment is typically due 30 to 45 days later. If you ever want to sell or trade the machine before the loan matures, you will need a payoff letter to clear the lien.
If you are also adding other machines to your fleet, we can bundle them. Many operators pair a combine with a Skid Steers financing package to handle grain handling and yard work under one master agreement.
Put the right equipment to work
From $5,000 to $5 million, new or used, Provide Capital helps businesses nationwide finance the equipment they need.
Apply TodayFrequently Asked Questions
Can I finance a used combine with no money down?
Zero-down programs exist for well-qualified buyers purchasing late-model, low-hour equipment. Most used combine deals, however, require 10% to 20% down. The down payment protects the lender’s collateral position and usually improves your rate range.
How old can a used combine be to qualify?
Many lenders set a 10- to 15-year age limit at origination. A 10-year-old combine on a 5-year term is 15 by payoff. Exceptions are possible for machines with documented low hours or recent rebuilds, but expect a larger down payment or shorter amortization.
Does the lender need to approve the private seller?
The lender cares more about the equipment than the seller, but the seller must be able to deliver clear title. If you are buying at auction, the auction house must agree to coordinate title transfer and lien release. Dealer sales are simpler because the dealer handles title workflow every day.
Can I finance attachments and headers with the combine?
Yes. Headers, yield monitors, grain carts and other attached equipment can usually be rolled into the same financing package as long as the total collateral value supports the loan amount. List every item on the purchase agreement.
Will a prior bankruptcy prevent approval?
Not necessarily. Many programs consider borrowers with a bankruptcy discharged two or more years ago. The key is what has happened since: re-established credit, stable farm income and a reasonable down payment all help. Rates vary by credit profile, equipment age and term, so expect a different range than a borrower with clean credit.
How long does approval take?
Simple deals under $250,000 can receive same-day approval when the application and equipment details are complete. Larger requests or requests requiring full financials may take 24 to 48 hours. You can speed the process by having your tax returns, equipment specs and seller contact ready.
Is the combine itself the collateral?
Yes. In most cases the combine secures the loan, which means you do not need to pledge farmland or other assets. That is a major advantage of equipment financing over general working-capital loans. The SBA’s 7(a) loan program can also be used for equipment, but it often requires additional collateral and longer processing.
Can I pay off the loan early?
Most equipment finance agreements allow early payoff, though some include a prepayment penalty in the first 12 to 24 months. Ask your specialist to show you the payoff schedule before you sign. If you expect a large crop insurance payment or land-sale proceeds within the first year, structure the loan with no prepayment penalty.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Provide Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.