
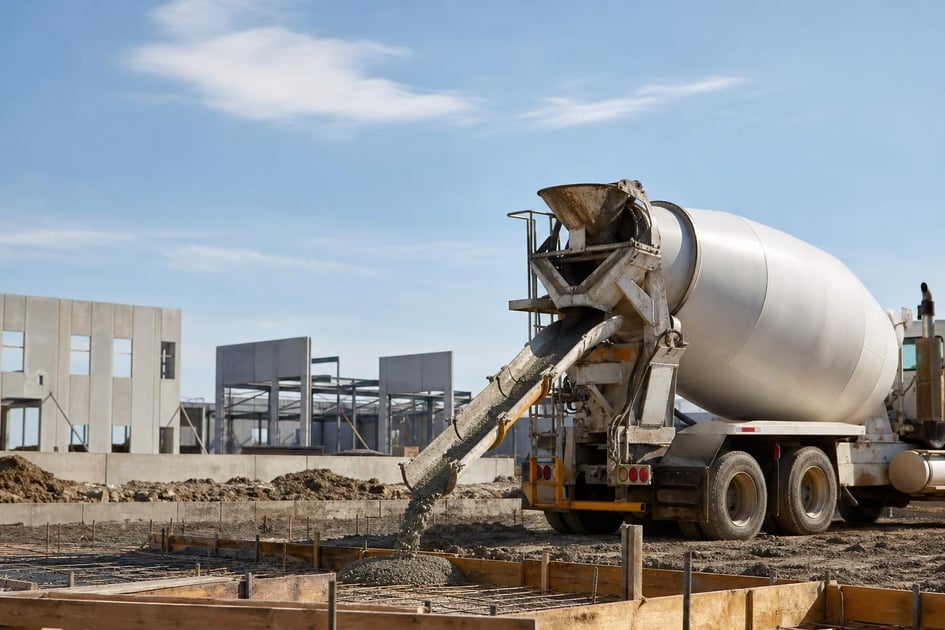
How Concrete Mixer Financing Works for Small Businesses
If you need a concrete mixer to take on larger pours or stop renting by the day, financing lets you spread the cost over the useful life of the machine while you start earning with it immediately. At Provide Capital, we finance new and used business equipment from $5,000 to $5 million, with the equipment itself serving as collateral. That collateral structure keeps rates competitive compared with unsecured borrowing. Same-day approvals are possible once we have a complete file, and we serve construction, landscaping, masonry, and related trades nationwide. According to U.S. Census Bureau data, construction activity supports steady demand for concrete equipment across regions.
Financing a concrete mixer works like most Concrete Mixer financing agreements. You select the unit, provide a short list of documents, and we run a credit review focused on your business cash flow and the asset value. Because the mixer secures the note, lenders weight the equipment condition and resale market more heavily than they would for an unsecured line. Rates vary by credit profile, equipment age and term, so a contractor with established revenue buying a two-year-old rear-discharge mixer will see different numbers than a startup-equivalent buyer looking at a twenty-year-old chassis.
Key Insight: Lenders price concrete mixer deals in part based on the hourly meter reading and chassis condition, not just the borrower's credit score. A well-maintained used mixer with documented service history often earns better terms than a neglected newer unit with no records.
What Determines Your Monthly Payment
Three factors drive your payment more than anything else: your business and personal credit profile, the age and type of mixer, and the length of the repayment term.
Credit profile includes both your business history and personal credit. Most small-business equipment lenders look for a minimum time in business, often two years or more, though some programs accept shorter histories with additional documentation. Revenue consistency matters because the lender wants evidence that your monthly cash flow can absorb the payment even in slower seasons.
Equipment age shapes both rate and term. New mixers and late-model used units qualify for longer terms and lower rates because the collateral retains value. Older mixers—especially those over ten years—may still finance, but the term usually shortens to match remaining useful life, which raises the monthly payment. Rates vary by credit profile, equipment age and term, so the only way to pin down a payment is to run the specific deal.
Down payment also moves the number. While some transactions close with zero down, putting 10 to 20 percent down improves the rate and keeps the payment in line with cash flow. On a $75,000 mixer, a 15 percent down payment cuts the financed amount to $63,750 and signals to the underwriter that you have skin in the deal.
New vs. Used Concrete Mixers: Financing Considerations
New Mixers
New concrete mixers arrive with manufacturer warranties, predictable maintenance schedules, and the latest environmental compliance. For buyers doing municipal or state work, a new unit may be required to meet idling and emissions specs. Financing terms on new equipment typically stretch to five to seven years, keeping payments low. The downside is depreciation: a new mixer loses significant value in the first two years, so you will owe more than resale value early in the loan unless you put money down.
Used and Refurbished Mixers
Used mixers dominate the small-contractor market because they deliver production capacity without the first-owner depreciation hit. A three- to five-year-old rear-discharge mixer often sells for 40 to 60 percent below original sticker while retaining a decade of service life. Financing used equipment requires a careful inspection. Check the drum bearings, hydraulic pump condition, and chassis rust. Ask for maintenance logs. If you buy at auction, expect the lender to require an independent appraisal before funding. Terms on quality used mixers usually run three to five years.
Pro Tip: If you are comparing a new $120,000 mixer against a used $65,000 unit, run the numbers on total cost of ownership, not just monthly payment. Include expected maintenance, downtime, and fuel. A cheaper used mixer that spends three weeks in the shop during peak season can cost more than the new unit.
Lease vs. Loan: Which Structure Fits Your Job Mix
You can acquire a concrete mixer through an equipment loan or a lease. A loan puts the title in your name; a lease keeps title with the lessor until you exercise a purchase option. The right choice depends on how long you plan to keep the mixer, how many hours you expect to run it annually, and your tax strategy for the 2026 tax year.
Loans make sense for contractors who plan to run the mixer for seven to ten years and want to build equity. Each payment reduces the principal, and at the end you own a debt-free asset that still has resale value. Loans also let you claim depreciation and, for the 2026 tax year, any available Section 179 deduction, subject to IRS limits and your CPA's advice.
Leases work well if you replace equipment every three to five years to avoid major maintenance, or if you need the lowest possible monthly outlay to preserve cash for labor and materials. A $1 buyout lease functions almost like a loan, while a fair-market-value lease gives the lowest payment but requires you to return or refinance the unit at term end. Talk to your accountant about whether you can deduct lease payments as a business expense in 2026.
| Feature | Equipment Loan | FMV Lease |
|---|---|---|
| Ownership | You own from day one | Lessor owns; you have option to buy |
| Monthly payment | Higher than FMV lease | Lowest payment option |
| Term length | 3–7 years typical | 2–5 years typical |
| End of term | No balloon; free and clear | Return, renew, or buy at fair market value |
| Tax treatment | Depreciation and possible Section 179 | Payments may be deductible as expense |
| Best for | Long-term keepers | Frequent upgraders or cash conservation |
Forbes has noted that equipment financing remains a preferred strategy for owner-operators who need to preserve working capital while scaling capacity. If you know which structure fits your jobs, see what you qualify for and we can run both scenarios on the same mixer.
Tax Treatment for the 2026 Tax Year
For the 2026 tax year, the IRS allows businesses to deduct the cost of qualifying equipment under Section 179, subject to annual limits and phase-out thresholds that adjust for inflation. Concrete mixers generally qualify because they are used more than 50 percent for business. However, the exact dollar limits for 2026 depend on final inflation adjustments, so you should consult your CPA before counting on a specific deduction amount.
Bonus depreciation may also apply to new and used concrete mixers placed in service during 2026, though the percentage has been stepping down in recent years. Your accountant can tell you whether bonus depreciation, Section 179, or regular MACRS depreciation delivers the best outcome for your 2026 return. Do not make a purchase decision solely for tax purposes without confirming the numbers for this specific tax year.
By the Numbers: A contractor in the 24 percent federal tax bracket who deducts a $60,000 mixer in 2026 could see a tax savings of roughly $14,400, but only if the full deduction is available under current-year limits and the equipment is placed in service before December 31, 2026. Confirm with your CPA.
Who Qualifies for Concrete Mixer Financing
Time in Business and Revenue
Most equipment lenders prefer two or more years in business, but programs exist for newer contractors with strong personal credit and documented revenue. The U.S. Small Business Administration recommends that businesses evaluate equipment costs against expected revenue before taking on debt. Monthly revenue of $10,000 to $15,000 or more improves approval odds, though there is no universal minimum. We look at bank deposits, tax returns, and existing contracts to verify that the payment is sustainable.
Credit Profile
A personal FICO score in the mid-600s or higher opens the most competitive programs. Scores below that do not automatically disqualify you, but the rate and down-payment requirement adjust to reflect risk. If your credit has recent blemishes, be prepared to explain them and show compensating factors such as rising revenue or a large down payment.
Down Payment and Collateral
Down payments range from zero to 20 percent depending on credit and equipment age. Because the mixer secures the financing, lenders also care about the serial number, year, make, model, and seller reputation. Buying from a licensed dealer usually streamlines approval compared with a private-party sale, though both are financeable.
Industry-Specific Use Cases
Construction and General Contracting
Concrete work is the backbone of commercial and residential construction. A general contractor who subbed out flatwork for years can bring that revenue in-house with a mixer that pays for itself in eighteen to twenty-four months if utilization stays above sixty percent. Construction equipment financing covers not just the mixer but also conveyors, saws, and vibrators that keep the pour moving.
Landscaping and Hardscaping
Hardscape crews building retaining walls, outdoor kitchens, and pool decks need small-batch concrete on tight schedules. A towable mixer or mini ready-mix truck lets them control delivery timing and mix design. These units typically fall in the $5,000 to $35,000 range, well within our minimum.
Masonry and Specialty Trades
Brick and block contractors use mortar mixers daily. While mortar mixers differ from concrete transit mixers, the financing process is similar. If your crew does both flatwork and masonry, a combo purchase of Concrete Equipment financing and related tools can sometimes bundle into a single facility.
Common Mistakes When Financing Mixers
Buying undersized is the most expensive error. A contractor who wins a parking-lot contract but shows up with a two-yard towable mixer spends more on labor and downtime than the monthly payment on a six-yard rear-discharge unit would have cost. Match the mixer capacity to your largest recurring job, not your smallest.
Skipping the pre-purchase inspection on used equipment is another costly mistake. Check the drum for cracks, the engine for blow-by, and the hydraulics for leaks. Ask for a oil analysis if the seller has no records.
Finally, do not stretch the term so far that you owe money after the mixer is worn out. A seven-year loan on a high-hour used unit can leave you underwater when the drum needs rebuilding. Keep the term aligned with expected useful life.
What Documentation You Need
The faster you gather paperwork, the faster we can issue a decision. Most concrete mixer deals close with the following: a driver's license, three months of business bank statements, the equipment quote or invoice, your most recent business tax return, and a voided business check for ACH setup. If the mixer is used and priced above $50,000, we may ask for an independent appraisal. Corporations and LLCs should also have articles of incorporation or operating agreements ready.
What Happens After Approval
Once approved, you will receive a term sheet outlining rate, payment, and any conditions. Review it, sign, and return with any stipulations such as proof of insurance. We pay the seller directly, typically within one to three business days after receiving signed documents and a clear title or lien release. Your first payment usually hits thirty days later. If you need the mixer on a job site by Monday, start the application by Wednesday to leave room for document collection and seller coordination.
Pro Tip: Coordinate your insurance bind date with the funding date. If you bind coverage three days before we pay the seller, you avoid a gap in coverage, and the lender sees continuous protection from day one.
Frequently Asked Questions
Can I finance a concrete mixer with challenged credit?
Yes, though the structure changes. Lower credit scores often require a larger down payment or a shorter term. Rates vary by credit profile, equipment age and term, so the best path is to submit a complete application and let the underwriter match you to the right program rather than assume disqualification.
How long does approval take?
Same-day approvals are possible when the file is complete. If we need additional documentation—such as a missing tax return or a used-equipment appraisal—expect one to two additional business days.
Is a down payment always required?
No. Zero-down programs exist for strong credits and new equipment. Used mixers and lower credit profiles more commonly require 10 to 20 percent down. The down payment reduces your financed amount and monthly obligation.
Can I finance a used or auction mixer?
Yes. We finance new and used business equipment. Auction purchases may require a third-party inspection and a quick closing timeline, so get pre-approved before bidding.
What term lengths are available?
Terms typically range from two to seven years. New mixers qualify for longer terms; used units and lower credit files align with shorter terms. Pick the term that keeps the payment manageable without extending past the equipment's useful life.
Does the lender need to approve the seller?
Usually no, but the seller must provide clear title and a valid invoice. Private-party sales require extra title verification. Licensed dealers streamline the process because they handle title transfers regularly.
Can I pay off the loan early?
Most equipment loans allow early payoff. Some carry a prepayment penalty in the first twelve to twenty-four months; others do not. Review your term sheet for the specific structure before signing.
What insurance is required?
You must carry physical damage insurance on the mixer naming the lender as loss payee. General liability and any state-required auto or inland marine coverage should also stay current.
Next Steps
A concrete mixer should earn more than it costs. Run your utilization hours, compare new and used options, decide whether a loan or lease fits your 2026 tax plan, and gather your documents. Then talk to a specialist about your specific mixer and get a same-day decision on your equipment. We finance deals from $5,000 to $5 million for contractors nationwide, and the equipment itself is the collateral that keeps your rate competitive.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Provide Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.
